

Solutions
Securely accept, manage, and make payments through one point of integration


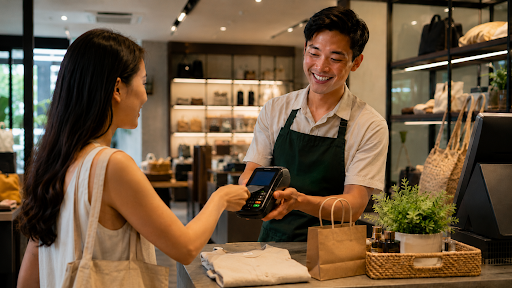
Not sure which card terminal fits your business? From countertop EDC machines to softPOS on a smartphone, here’s a simple guide to choosing a POS terminal that supports growth across Southeast Asia.
For many businesses, digital transformation starts online. However, the physical checkout experience remains one of the most important customer touchpoints. Whether you operate a retail store, restaurant, hotel, clinic or service business, your ability to accept payments quickly and securely can directly influence customer satisfaction and sales.
This is where a POS terminal becomes essential.
A POS (Point of Sale) terminal allows businesses to accept card payments, contactless transactions, mobile wallets and other digital payment methods at physical locations. Depending on the device and payment provider, some EDC terminals can also support QR code-based payments. In Thailand, for example, merchants may want to consider support for PromptPay alongside card and contactless payments, depending on their customers’ preferences and business needs. Across Southeast Asia, these devices are commonly referred to as EDC machines, card terminals, card machines, mesin EDC (Indonesia) or máy POS (Vietnam). In Indonesia, some smaller merchants also use the term mesin kasir loosely to describe their till and card-payment set-up. However, it technically refers to the cash register, not the card device itself.
As consumer preferences continue shifting towards cashless payments, choosing the right POS terminal has become a strategic business decision rather than simply an operational necessity.
A POS terminal is a payment acceptance device that enables merchants to process transactions in-store.
Modern POS terminals can accept:
Unlike traditional cash registers, today’s POS terminals often connect to broader payment ecosystems, allowing businesses to consolidate reporting, manage multiple payment channels, and support omnichannel customer journeys.
Customer expectations have changed significantly over the past decade.
Many shoppers now move seamlessly between online and offline channels. They may discover products online, visit a physical store to complete the purchase, and expect the same payment convenience throughout their journey.
Businesses that offer flexible payment options often benefit from:
For growing merchants, the right POS setup can also help bridge online and offline sales channels, creating a more unified commerce experience.
These are fixed payment devices typically found at checkout counters.
Best suited for:
They offer stable connectivity and are often integrated directly with cashier systems.
Portable terminals use Wi-Fi or mobile connectivity, letting staff accept payments anywhere in a store.
Best suited for:
These devices improve customer convenience by bringing payment acceptance directly to the customer.
Mobile POS solutions turn smartphones or tablets into payment acceptance devices.
Merchants can use compact card readers or tap-to-pay functionality on compatible devices to accept payments without investing in extensive hardware.
Best suited for:
SoftPOS (software point of sale) lets merchants accept contactless payments directly on a compatible NFC-enabled smartphone or other supported device, without a separate card terminal. Instead of relying on dedicated payment hardware, the device uses software to accept contactless payments, subject to the solution’s device, security, and payment scheme requirements.
Unlike traditional POS terminals, which use dedicated payment hardware, or mPOS setups that may require a separate card reader, softPOS can offer a more streamlined way to accept contactless payments with fewer hardware requirements.
SoftPOS may be suitable for:
When evaluating softPOS, merchants should check supported devices, accepted payment methods, security requirements and integration options to ensure the solution meets their business needs.
These combine payment acceptance with inventory management, sales reporting and customer management features.
Integrated solutions are popular among merchants seeking a unified operational platform rather than standalone payment devices.
For merchants in Thailand, choosing an EDC machine involves more than selecting a card-reading device. Businesses may also need to support local QR payments, contactless transactions and integration with their existing checkout systems.
2C2P’s in-store payment solutions support an integrated approach to payment acceptance, connecting EDC payment terminals with its payment gateway. The Thailand sales offering includes several hardware options, such as the PAX A80 with PIN pad, the PAX A920 Pro and the BlueTap standalone payment terminal. The right device depends on the merchant’s checkout setup, connectivity requirements, and operational needs.
Through the 2C2P payment gateway, the in-store payment flow can support card payments, contactless transactions and QR payments such as PromptPay, alongside other supported payment methods. Depending on the merchant’s configuration and eligibility, the wider offering also includes instalment payments through participating bank partners and bank or loyalty point redemption.
For merchants operating across online and offline channels, this integrated approach can help connect in-store payment acceptance with broader payment processing, reporting and reconciliation workflows. Businesses should confirm device availability, supported payment methods, integration requirements and commercial terms with 2C2P before selecting a solution.
The first consideration should be payment flexibility.
Your POS terminal should support:
For merchants in Thailand, it is worth checking whether the solution supports PromptPay QR payments alongside the card and contactless options relevant to their business. Available payment methods can depend on the terminal, payment provider, merchant configuration, and applicable requirements, so confirm support before committing to a device.
Southeast Asia is one of the world’s most diverse payment markets. Supporting local customer preferences can help reduce checkout friction and improve conversion rates.
Today’s merchants increasingly operate across multiple channels.
A customer may:
Choosing a POS solution that integrates with your online payment infrastructure can help create a more seamless customer experience.
For example, 2C2P’s unified payment gateway connects in-store and online payment channels, with payment processing, reporting and reconciliation managed within its broader payment ecosystem. Merchants should confirm which integrations and features are available for their specific set-up.
Payment security should never be overlooked.
Look for providers that comply with industry security standards and work with recognised card schemes. Security features help protect both merchants and customers while reducing operational risk.
Managing multiple payment channels can become complex.
A modern POS solution should provide:
Consolidated reporting becomes particularly valuable for businesses operating across multiple locations.
Payment interruptions can directly impact revenue.
Evaluate:
For high-volume merchants, uptime is critical.
In many Southeast Asian markets, the terms are used interchangeably.
EDC stands for Electronic Data Capture, a term widely used by banks and payment providers across Indonesia, Malaysia and several neighbouring markets.
Generally:
Both refer to hardware that enables electronic payment acceptance at the point of sale.
Businesses researching mesin EDC, card terminals or card machines are often evaluating similar categories of payment acceptance technology.
Merchants expanding across Southeast Asia face additional challenges.
The region’s digital economy is projected to pass US$300 billion in gross merchandise value in 2025, according to the e-Conomy SEA 2025 report by Google, Temasek and Bain & Company, and independent research from the Visa Consumer Payment Attitudes Study confirms that cashless habits are now firmly embedded across the region’s major markets.
Each market has unique payment preferences:
For regional merchants, selecting a provider with broad payment coverage can reduce the complexity of managing separate integrations and vendor relationships across multiple countries. 2C2P supports more than 400 payment methods across Asia, helping businesses scale across diverse markets through a single payments ecosystem.
Before committing to a solution, consider asking:
The answers can significantly affect long-term operational efficiency and scalability.
A POS terminal is no longer just a device for accepting card payments.
For modern merchants, it serves as a critical connection point between customers, payment methods and business operations. The right solution should not only process transactions securely but also support omnichannel commerce, simplify reconciliation and provide the flexibility needed to grow across Southeast Asia.
As customer expectations continue to evolve, businesses that invest in scalable, integrated payment infrastructure will be better positioned to deliver seamless experiences across every touchpoint.
Whether you’re opening your first retail outlet or expanding across Southeast Asia, choosing the right POS terminal or EDC machine is essential to creating a smooth customer experience. 2C2P’s in-store payment solutions support payment acceptance through EDC terminals and other supported interfaces, with options for card, contactless and QR payments, including PromptPay where configured and supported.
For merchants in Thailand and across the region, 2C2P’s unified payment gateway can connect in-store and online payment channels within a broader payment ecosystem. Explore 2C2P’s in-store payment solutions to learn about available terminal options, supported payment methods, and integration possibilities for your business.
With omnichannel capabilities, consolidated reporting and access to over 400 payment methods across Asia, 2C2P helps merchants connect their online and offline payment experiences while supporting growth across multiple markets. Learn more about 2C2P’s in-store payment solutions and discover how your business can simplify payment acceptance at every customer touchpoint.
Contact us today.
 Login